
- नेशनल डेस्क
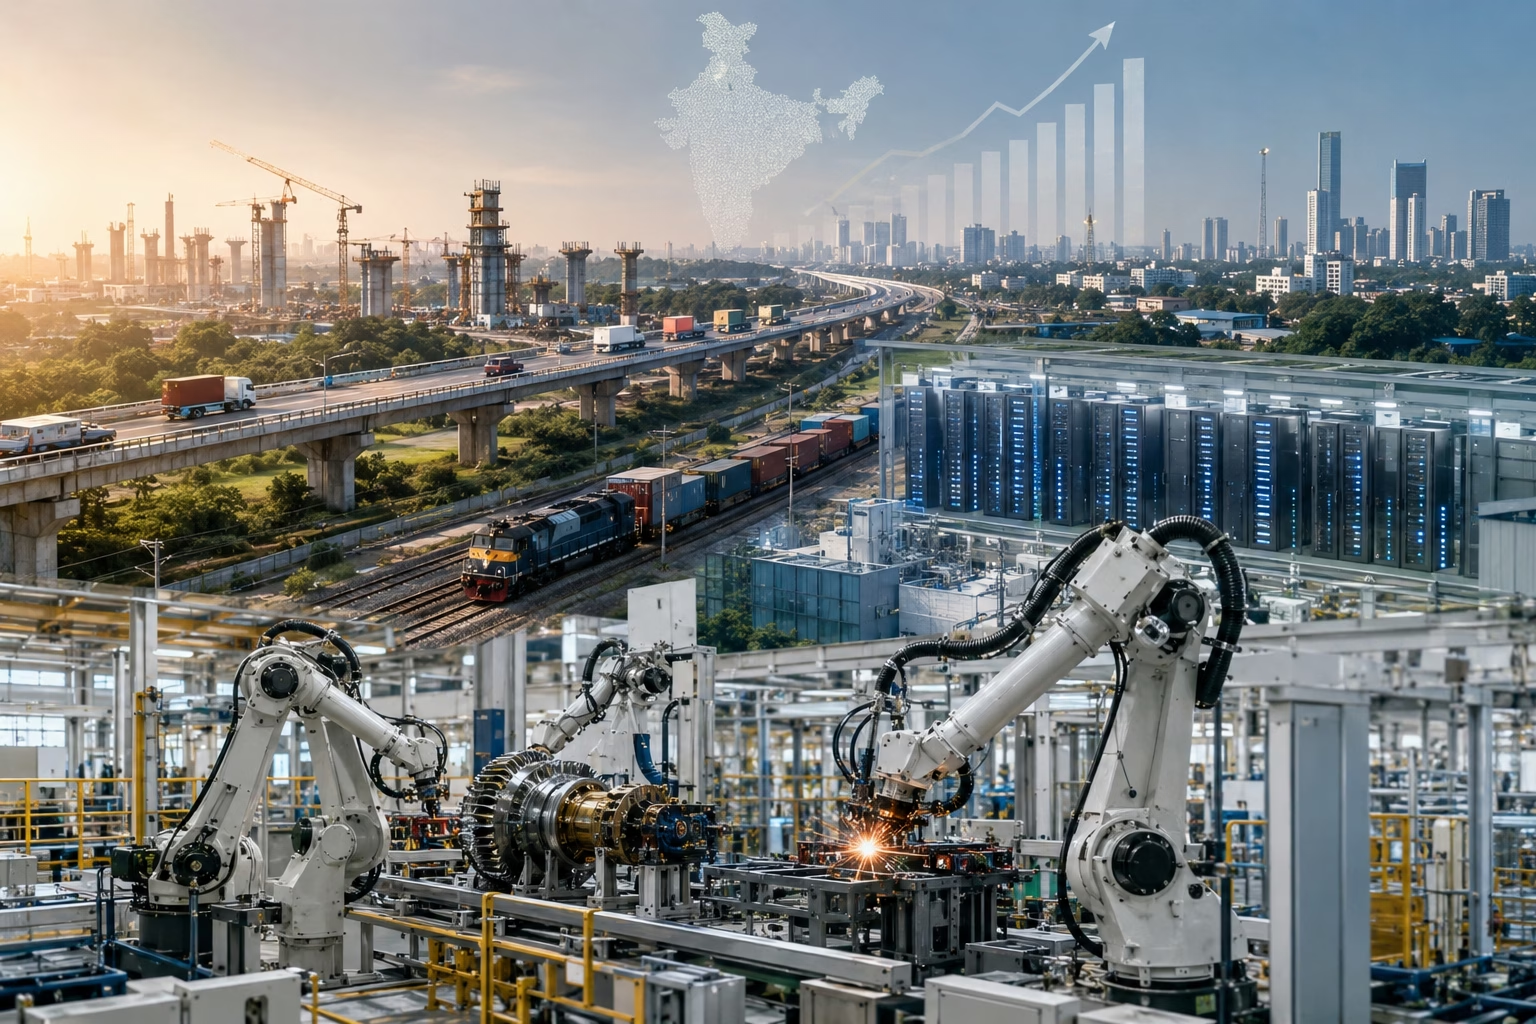
India Private Investment Revival : भारत की अर्थव्यवस्था ने वित्त वर्ष 2026-27 की पहली तिमाही में 7.8% वास्तविक GDP growth दर्ज की। इससे भी महत्वपूर्ण संकेत निवेश के मोर्चे से आया—Gross Fixed Capital Formation (GFCF) 11.9% बढ़ा, जबकि एक साल पहले इसी तिमाही में इसकी वृद्धि 5.8% थी। GDP में GFCF की हिस्सेदारी भी Q1 FY26 के 31.4% से बढ़कर 34.3% हो गई।
यह तस्वीर बताती है कि भारत की growth story में investment का वजन बढ़ रहा है। लेकिन इसे सीधे-सीधे “private investment boom” कहना जल्दबाजी होगी, क्योंकि GFCF के आंकड़े निवेशक की institutional category—सरकारी या निजी—को अपने आप अलग नहीं करते।
फिर भी corporate CAPEX के दूसरे उपलब्ध संकेत उत्साहजनक हैं। NSO के Forward-Looking CAPEX Survey में 2025-26 के लिए निजी कॉरपोरेट क्षेत्र का अनुमानित CAPEX ₹11.44 लाख करोड़ और 2026-27 के लिए reported investment intentions ₹9.55 लाख करोड़ रहे हैं।
Fact Sheet
- Real GDP Growth: 7.8%
- Real GVA Growth: 8.2%
- GFCF Growth: 11.9%
- GDP में GFCF Share: 34.3%
- Private Consumption Growth: 7.1%
- Exports Growth: 12.0%
- Manufacturing Growth: 9.2%
- Services Growth: 10.0%
- Financial, Real Estate, IT & Professional Services: 12.1%
- Capital Goods Production: 15.2%
सबसे बड़ा बदलाव: Growth में Investment का वजन बढ़ा
Q1 FY27 में भारत की real GDP growth 7.8% रही, जो पिछले साल की समान तिमाही के 6.9% से तेज है। लेकिन headline GDP से ज्यादा महत्वपूर्ण expenditure side का composition है।
GFCF 11.9% बढ़ा, जबकि Q1 FY26 में इसकी growth सिर्फ 5.8% थी। यानी fixed investment की गति में उल्लेखनीय acceleration हुआ है।
इसका अर्थ है कि अर्थव्यवस्था में केवल मौजूदा consumption ही नहीं, बल्कि नई productive capacity बनाने वाली activity भी तेज हुई है।
क्या यह Private Investment Revival है?
संकेत मजबूत हैं, लेकिन निष्कर्ष सावधानी से निकालना होगा।
GFCF में roads, buildings, machinery, equipment और अन्य fixed assets पर investment शामिल होता है। इसका 11.9% बढ़ना investment demand में तेजी दिखाता है, लेकिन इससे अकेले यह पता नहीं चलता कि कितना investment private companies ने किया और कितना government या अन्य institutional sectors ने।
Corporate CAPEX का दूसरा बड़ा संकेत
NSO के Forward-Looking Survey में निजी कॉरपोरेट क्षेत्र का 2025-26 का provisional aggregate CAPEX ₹11,43,879 करोड़ आंका गया।
सर्वे के अनुसार:
- 48.63% enterprises का focus core assets पर था।
- 38.36% existing assets में value addition की योजना बना रहे थे।
- 65.35% CAPEX internal accruals से finance होने का अनुमान था।
- 23.25% domestic debt से finance होने का अनुमान था।
- 2026-27 के लिए reported CAPEX intentions ₹9,55,281 करोड़ थीं।
यह महत्वपूर्ण इसलिए है क्योंकि internal accruals का बड़ा हिस्सा बताता है कि कंपनियां केवल borrowed money पर निर्भर होकर investment नहीं कर रही हैं; हालांकि survey intentions को actual expenditure के बराबर नहीं माना जाना चाहिए।
Manufacturing भी साथ दे रहा है
Investment cycle को manufacturing momentum का support मिल रहा है।
Q1 FY27 में:
Manufacturing: 9.2%
Secondary sector: 8.6%
Services: 10.0%
वहीं electrical equipment जैसे segments में production growth 27%, other transport equipment में 19.5% और computer, electronic एवं optical products में 12.4% रही।
इससे संकेत मिलता है कि investment story सिर्फ infrastructure तक सीमित नहीं है; manufacturing capacity और technology-linked sectors में भी activity मजबूत है।
Credit growth भी investment story को support कर रहा है
PIB के 1 सितंबर के economic factsheet के अनुसार जुलाई में industry को credit growth 20.0% और services को 22.9% रही। यह investment और business activity के लिए एक supportive financial backdrop का संकेत देता है।
हालांकि credit growth को सीधे CAPEX growth का पर्याय नहीं माना जा सकता।
Consumption की भूमिका खत्म नहीं हुई
Investment मजबूत हुआ है, लेकिन भारत की growth story अभी केवल investment-led नहीं है।
Private Final Consumption Expenditure यानी household consumption Q1 FY27 में 7.1% बढ़ा। Exports भी 12% बढ़े।
यानी वर्तमान growth mix में तीन महत्वपूर्ण pillars दिखाई दे रहे हैं:
Investment + Consumption + Exports
यही combination growth को अधिक broad-based बनाता है।
पहले क्या था और अब क्या बदल रहा है?
पिछले वर्षों में भारत की growth को मजबूत public capital expenditure, infrastructure spending और resilient consumption का सहारा मिला।
अब तस्वीर में एक अतिरिक्त तत्व ज्यादा स्पष्ट हो रहा है:
Public investment → Private investment crowd-in → Capacity expansion → Jobs/Income → Consumption
यदि यह cycle sustained रहती है तो इसका प्रभाव केवल GDP headline पर नहीं बल्कि:
- manufacturing capacity
- infrastructure
- employment
- corporate earnings
- bank credit
- productivity
- supply-chain localisation
पर भी पड़ सकता है।
सरकार के स्तर पर भी infrastructure investment को आगे बढ़ाने की कोशिश जारी है। जून 2026 में Cabinet ने NIIF के लिए अतिरिक्त ₹30,000 करोड़ का investment commitment मंजूर किया, जिससे सरकार की कुल commitment ₹60,000 करोड़ हो गई।
लेकिन तीन बड़े सवाल अभी बाकी हैं
1. क्या CAPEX intentions actual investment में बदलेंगे?
Survey में future investment intentions मजबूत हैं, लेकिन intention और actual spending में अंतर हो सकता है। इसलिए अगले quarters के corporate expenditure data ज्यादा महत्वपूर्ण होंगे।
2. क्या private investment व्यापक sectors में फैलेगा?
Data centres, infrastructure, electronics और advanced manufacturing जैसे sectors में activity मजबूत दिख रही है। अब सवाल है कि यह momentum छोटे और मध्यम businesses तथा broader manufacturing ecosystem तक कितना पहुंचेगा।
3. क्या external shocks recovery को रोक सकते हैं?
High oil prices, geopolitical tensions, global trade uncertainty और rupee pressure भारत की investment story के लिए risks बने हुए हैं। Reuters के अनुसार analysts ने भी इन external pressures को आगे growth के लिए प्रमुख risk बताया है।
What Next?
आने वाली तिमाहियों में इन indicators पर नजर रखना सबसे उपयोगी होगा:
Corporate CAPEX actual spending
↓
Capital goods production
↓
Bank credit to industry
↓
Private-sector project announcements
↓
Capacity utilisation
↓
Employment generation
↓
Corporate earnings
अगर इन सभी में sustained improvement दिखाई देता है, तभी यह कहना ज्यादा मजबूत होगा कि भारत ने एक टिकाऊ private investment cycle में प्रवेश कर लिया है।
Bottom Line
भारत की Growth Story में investment का momentum निश्चित रूप से मजबूत हुआ है।
Q1 FY27 में GDP 7.8%, GFCF 11.9%, manufacturing 9.2% और services 10% की growth इस दिशा में मजबूत संकेत देती है।
लेकिन सबसे महत्वपूर्ण editorial निष्कर्ष यह है:
यह अभी “Private Investment Boom” की definitive confirmation नहीं, बल्कि “Investment Cycle के मजबूत होने और Private CAPEX Revival के उभरते संकेतों” की कहानी है।
अगले कुछ quarters यह तय करेंगे कि यह acceleration temporary rebound है या भारत की growth story का structural shift।
Primary Verification: MoSPI/PIB economic data; supporting analysis from Reuters.
Discover more from
Subscribe to get the latest posts sent to your email.